Steel Kitten: early retirement

Showing posts with label early retirement. Show all posts

I took two half days off work this week to tackle our finances. A lot of things have happened at once and I needed some solid time to review and organise things.

Savings

I've been trying to find places for our savings with good interest rates now our Coventry Building Society Regular Savers have matured. To compound this, I received a letter from Tesco letting me know they are ditching their current accounts in November. I've been using our account as a savings account, as it was offering 3% on balances up to £3,000, although we kept a lot more in there. This dropped last year to 1% and continues to fall so I have to find a home for those savings. 

Some of the accounts with the best rates are for existing customers, others are only for people living in a specific postcode. Some that look ok will only take very small maximum deposit limits and so are not worth the hassle of setting them up. 

We already have Stock and Shares ISAs which we use those specifically for investing for my retirement, and I don't want to reduce our annual limits by opening up a cash ISA.

I've looked at premium bonds but I actually don't like the lottery aspect of it. According to MSE's premium bond calculator I could be looking at about £75 in prizes for the amount I would buy, but that is obviously based on chance. I could get more but it is statistically likely I will get less.

I've never been keen on tying my money up for a fixed term, in case we have an emergency and need the money, but I'm slowly coming round to the idea as some of the better rates on the market are fixed term accounts. 

After much research the only options that suits my specific requirements are a 12-month fixed term account with Oak North Bank for 1.23% interest and/or a regular savings account with Coventry Building Society at 1.05%. That's a lower interest rate than last year but it allows larger monthly deposits so is simpler to maintain, and crucially, I can still access the latter if I need it. 


-oOo-


Retirement accounts

Once that decision was made I turned my attention to Martin's accounts. His SIPP is being transferred to Vanguard from BestInvest, as the latter's drawdown costs were far too expensive. I'm looking to keep that invested for the rest of the year and start drawdown after April next year. Our aim is to keep Martin's income under the Personal Allowance of £12,570, which we won't be able to do this year due to him working his last two months in the new financial year. Once we add in his occupational pension the SIPP will put him over. 

However, I noticed last week that his monthly pension statement stated HMRC has given him a Basic Rate tax code, which is not correct and means he is being taxed at 20%, despite only having a small pension as income. That tax code is often given to people who have pensions and are still working. So, we rang up HMRC, talked through the issue with them and they have now changed the tax code to account for this. He should now get a refund on the tax taken from his pension since June and a refund of the tax he paid during April and May while working. 


-oOo-


Credit cards

Finally credit cards. One of my 0% rate promotions is coming to an end in September. If you've read my blog for a while you'll know I favour putting larger spends on these cards, paying back a set amount and keeping my savings earning interest. It's a technique called stoozing. Because I have savings I can pay off the debt at any time if I need to so I don't feel burdened by it, but I get the luxury of repaying it at my leisure over time. The card repayments come from our income every month so my savings and investments can sit there untouched from one year to the next. 

After searching the market, I found a Marks and Spencer card that offers 0% interest for 20 months and was successful with my application. The car we bought last week was purchased using our normal household credit card to get the buyer's protection, and originally I was going to use a combination of my bonus and savings for that but I've decided not to so that balance will shortly be transferred onto the Marks and Spencer card. I'll then set up a regular payment every month and just forget about it. We will be renewing our mortgage deal in a couple of years and so I'll clear the balance three months before our new deal. 

There is another technique to saving/making money using credit cards but it's not as easy as it used to be so I don't do it. It's called a Super Balance Transfer or Money Transfer. Basically, you get a card with a 0% interest rate on money transfers and a low fee, then do a money advance off the card, up to the credit limit you've been given, into your current account. You're effectively taking a cash advance from your card. You can then put the cash into a savings account and get the interest. This is not so easy to do as it was 10 years ago. Back in the day there were very little, if any fees, for cash advances and huge savings interest so it was quite lucrative, but credit card lenders didn't like people doing it so changed their terms and conditions, the fees have increased massively (lowest is currently 3%), and savings interest rates are low.

You can still do it, but you need a special Money Transfer credit card but really it is too much faff for no reward so I stick to the stoozing. The only way I would change my mind is if we had a recession and the price of the funds in my pension and ISAs dropped significantly, making it worthwhile to buy the lower priced units in anticipation of the day they increase in value. I've done that before during a market dip, using savings though not money transfers. 

It's still good to have that possibility in my back pocket. I may need to use every means available to me if I'm to retire early. 


My week of annual leave passed by all too quickly and work looms tomorrow. 

Still, I managed to get done a lot of the things I wanted too, including a trip on Thursday to David Austin's rose gardens and plant centre over near Wolverhampton. Beautiful roses and now was definitely the right time to visit, as almost every rose was in bloom. I have a ridiculous amount of photos of my favourites to pore over for ideas.


The one above is stunning - a ground cover rose called Raubritter.


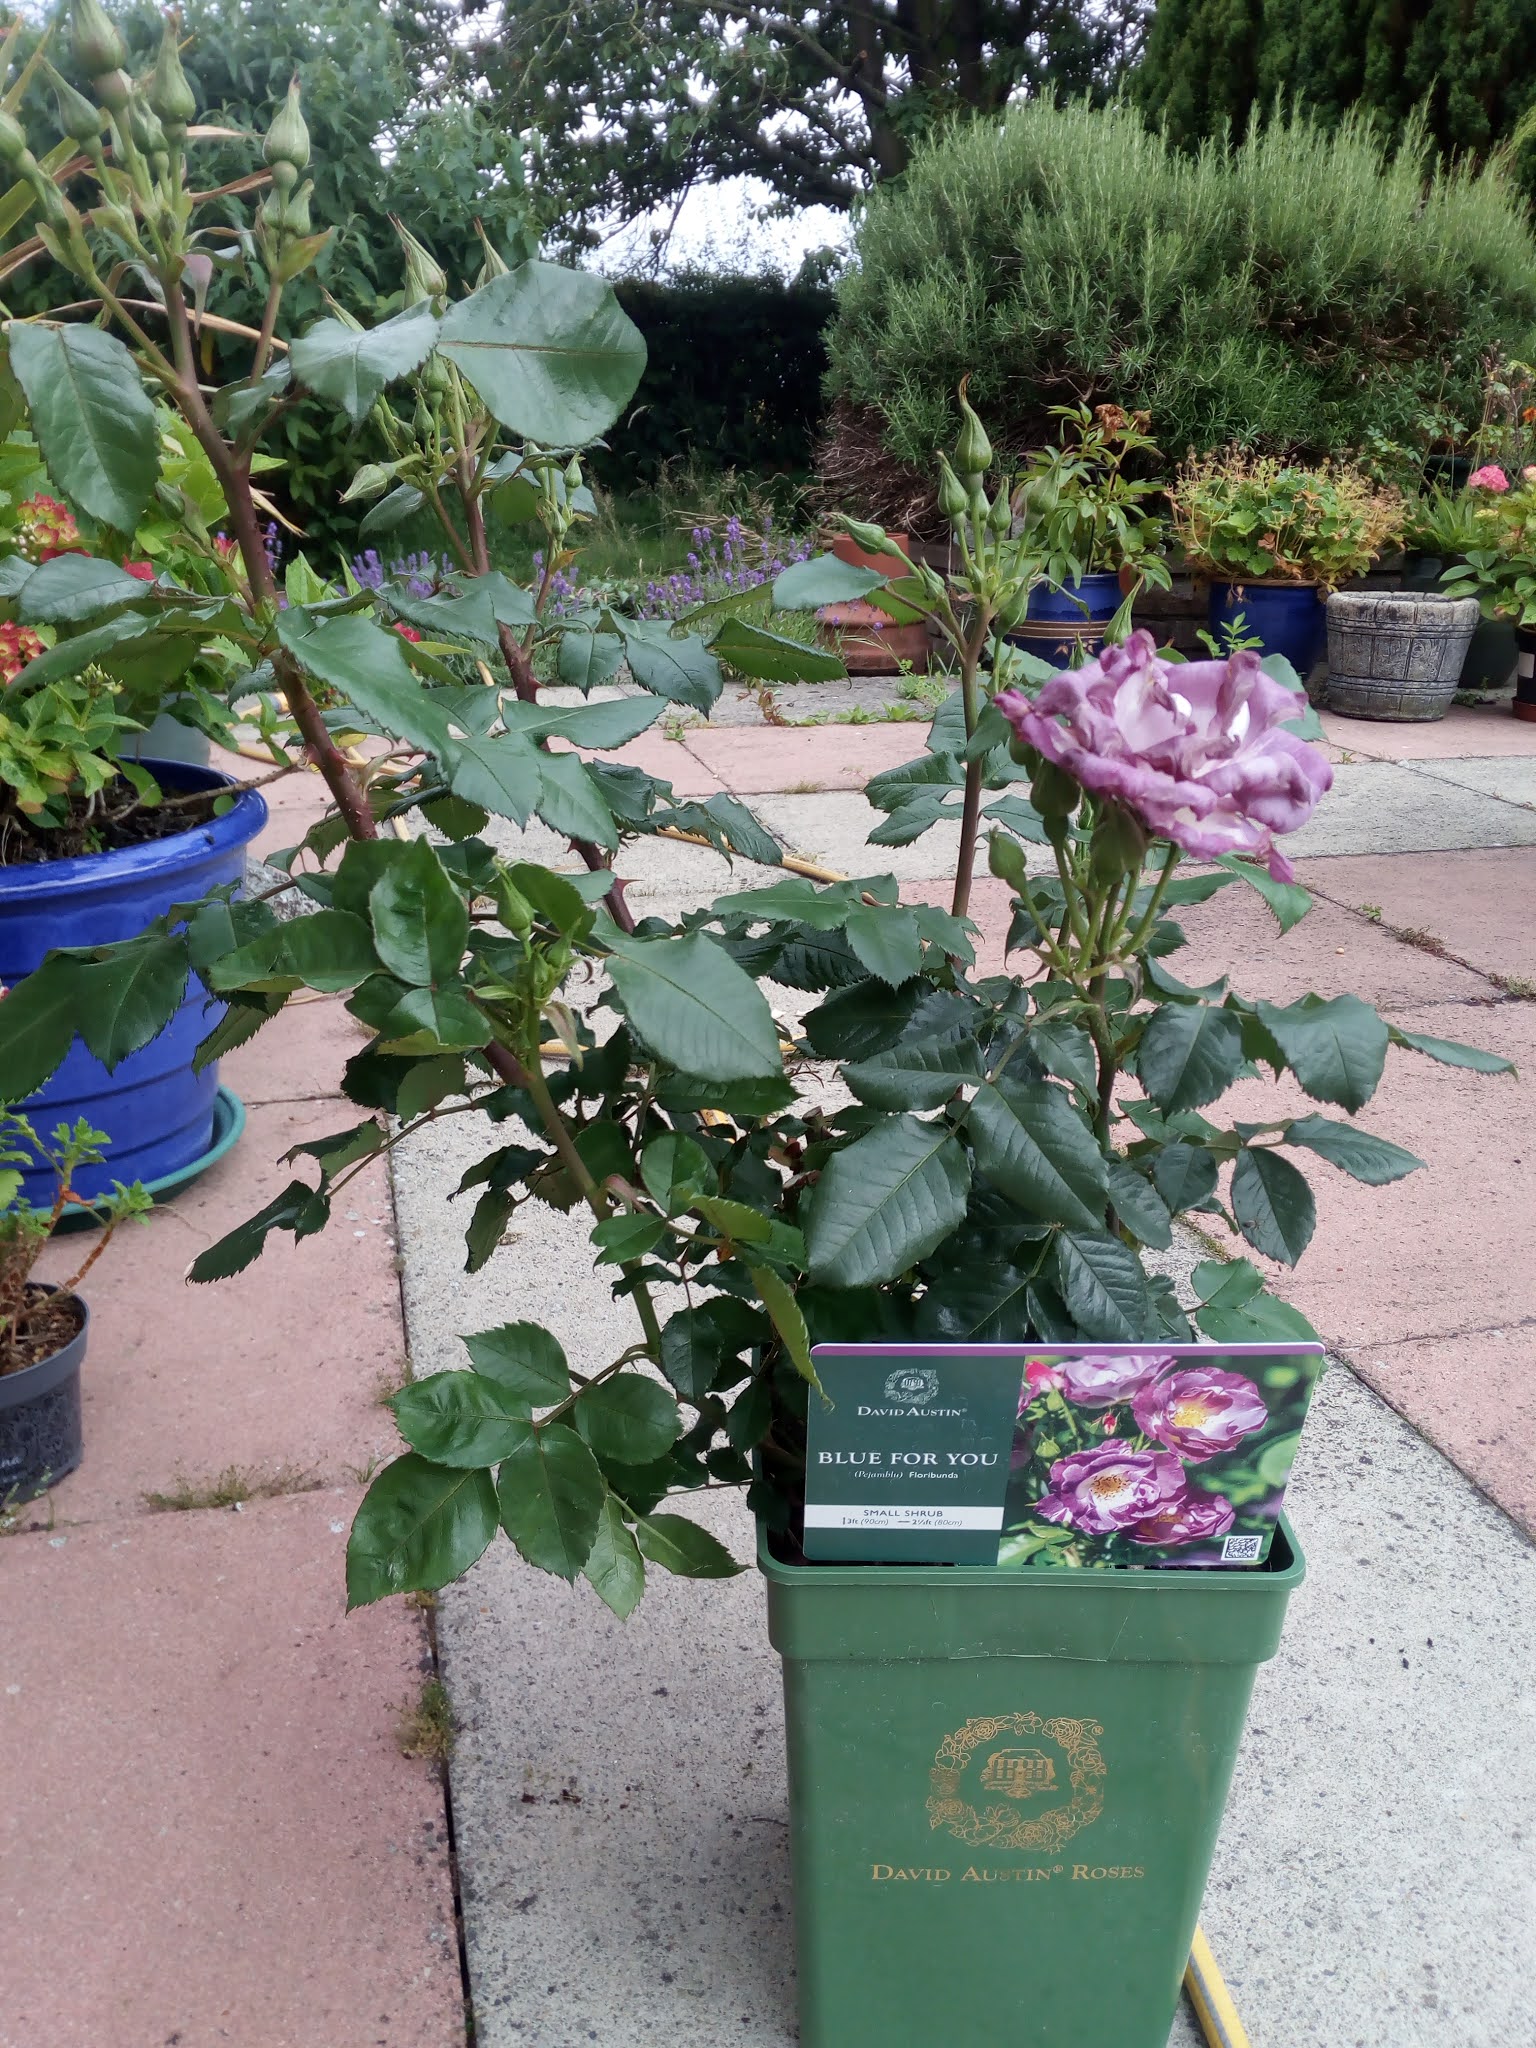
This one was a lovely mauve colour with yellow centres called Blue for You. Very strong fruity scent.


And this one - Old Pink Moss - was a very close match to the rose that I found in the churchyard when scattering my mother's ashes. Again, very strong scent.

I was incredibly restrained and came away with only one rose - Blue for You.


I do intend to buy Old Pink Moss at some point. Raubritter is also a contender just for its sheer exuberance. It is ridiculously prolific - it immediately cheers me up just looking at it. David Austin does have incredibly healthy good quality roses. I've got some in the garden already. This is Gertrude Jekyll out by the back door. 


-oOo-

 
I was in Lidl's on Friday and I happened upon one of these - the £1.50 fruit and veg box. 


I'd heard about these mythical creatures on various frugal blogs but never actually seen one in the flesh. That's because I was looking in the wrong place. My local Lidl keeps them by the tills, not in the fresh produce section where I had been looking. I decided to road test one. 


Absolutely gob-smacked at the sheer amount of stuff here, especially the amount of fruit. There were  another two large potatoes that aren't in the picture because I put them to the side out of shot when unpacking. This will last us most of the week. I already had a cauliflower in the fridge so today I'm going to use all of it up by doing a large dish of cauliflower in white sauce. I'll freeze half and the rest will be for dinner tonight to go with a lamb casserole I made yesterday. I've also got a vegetable lasagne to do for the freezer to use up some aging veg so I might lose the aubergine in there, perhaps slice it up and use it to replace some of the pasta sheets. 

-oOo-

After my last post Maria asked me about the gluten free cake recipe I used. 


It’s a basic mix that I used for non-gluten free Victoria Sponge cakes but I swopped in Doves Farm self-raising flour and made up only about a quarter of what I normally do, so only 2-3oz of butter, sugar and flour, 1 egg, bit of baking powder and vanilla essence, 1oz of flour for ground almonds and the fruit sliced on top. I gleaned from the internet that the key to gluten free baking is to make it a bit wetter than you think you should so I thought in this case the fruit would add the needed liquid as it cooked down. However, it seemed to make a very damp cake and while very tasty it was thin and fell apart easily. I decided to go back and do it again, this time doubling the amount of mixture to make it sturdier. In effect I was making one layer of what would have been a Victoria sponge.


I should add I also had a plan B, which I believe is essential to successful cooking. If it didn’t work I could dump it in a bowl with some cream and make it look like a deliberate effort at a dessert. 


Good that I had that plan because it didn't work 😁


Well, it sort of worked. The fruit disappeared into the depths of the cake. I see now why sponge flans were invented. 


Still tasted lovely but I may not worry about trying to perfect this. I think this is a case of how fruit behaves in a sponge unless the sponge is baked first and you add the fruit later (i.e. a flan). 


-oOo-


I was heavily focused on financial stuff this weekend. I've worked out that to retire at 55 (in seven years) I need to have a minimum of £350,000 and we're already a good part of the way there, which is encouraging. I used Guiide and Firecalc for the basic calculations, which showed me that £350000 will give me a 91% chance of retiring without running out of money. For a 98% chance of never running out of money I need £400,000. Up until last month I couldn't see how it was possible to build this because we needed the money we had saved to cover the shortfall between Martin's former salary and current pension income. However, a combination of my recent pay increase, Martin no longer having work expenses and our reduced spending has shown me that actually it is possible. This month we are on track to pay all of the bills without touching any of our savings. Every month that the savings stay the same or increase brings my retirement that little bit closer. 


I've not included everything in the figures. Inheritances are excluded, even those we have been told we should get later this year, as to me that is an added bonus. Until that money lands in our bank account it isn't real. I have also ignored the house equity, keeping that 'in reserve'. The plan is that sooner or later Martin and I are going to downsize - perhaps 7-10 years - at which point the remainder of the mortgage will be paid off and we will have some extra cash in the bank for our retirement. If it all goes wrong over the next few years, if the markets take a heavy downturn and take years to recover, if I become ill and can't work or lose my job and can't find another, then there is always that to fall back on.


Last Tuesday I made myself a fresh coffee, settled into my work chair, grabbed my planner and began my usual routine of daily organisation. There was a 'ping' from my phone and a calendar reminder came up - 'Hedges by 1st March'. My schedule for the week suddenly went out the window. 


I had completely forgotten that our boundary hedges had to be cut before the cut-off date of 1st March so we don't disrupt the nesting activity of the birds. It's in our deeds to do the hedges so the farmer can get his combine harvester into the field to cut the crops in the autumn. A hasty Zoom call to my boss and I managed to secure Wednesday and Thursday off work to try and get the bulk of the cutting done. 


Luckily I didn't have to do as much as I feared. We had cut back some overgrown laurel bushes at the front of the property in October so people could walk on the grass strip and not in the road. Also one side of the smallholding has very little hedge and more trees so that rarely needs anything, just big branches once in a while if they look like they'll catch the combine's cab as it passes. The area I needed to cover was actually only on two sides of the smallholding. All told, I had approx 160m horizontal cutting on the outside and 55m on the inside, and 80 metres of vertical cutting to take down the height. That's a lot of cutting. 


Wednesday was horrendous - high winds and 35mph gusts don't work well against with hedge trimmers and chainsaws but I managed to get some done. Cracked on again the next day and by 4pm I had manage to get about 80% of what I needed to do. I finally completed the task on Sunday in just a strappy top as it was so hot in the afternoon! All told, it took me approximately 14 hours.


I had a few dramas along the way. I have a small electric chainsaw, nice and light for a small person like me, but occasionally the chain jumps off so I have to put it back on. 


Luckily it's simple to do. 


So, over the next few weeks I'll finalise the hedge trimming all over the property, save the big stuff for the fire and the non-thorny stuff for kindling, then the rest goes on the growing pile in the paddock for a nice man with an industrial chipper to come late April to reduce it to a lovely pile of wood chip to rot down. 


The cats have loved the sunny weather this weekend. Prior to that the high wind meant they spent a lot of time indoors next to me. Baldrick wants to burrow and prefers to sleep like a toddler under a blanket...


...Missy just wants to snuggle...


And Georgie? He's just being an old cat with dementia, an overactive thyroid and arthritis. We keep him warm, medicated, and well fed and try not to get annoyed when he goes for a head rub and then bites us.

*****

I alluded to some big news in my previous post and now I have my hedging whinge out the way I shall tell you.


Martin will be retiring this year. 


Two major things have happened which has accelerated our plans for his retirement two years ahead of schedule.


1) We've found out that Martin can take some of his pension now. I hadn't appreciated that with every change of pension scheme Royal Mail made they dedicated the old fund to specific retirement milestones that can be taken without affecting the other bits. So the Final Salary scheme that closed in 2008 make up his Age 60 benefits while the Defined Contribution pension that ran from 2009 to 2018 make up his age 60 benefits. The current Defined Contribution pension accumulates and is used to pay out his 25% lump sum if he wants it (and we do). My widow's pension if he dies is the same whether we take the lump sum or not so I want to take it now and stash the cash because with COVID who knows what the future holds. So, there's a lump sum payment plus pension income to come from March. 


2) One of Martin's aunts has died, leaving a small legacy to him. It amounts to replacement salary and what we would be putting away into pensions over the next two years so Martin could retire at 62. 


We rolled around the house in a bit of a daze for a week, before sitting down and coming up with a plan of attack for the next few months. Then we found out that Royal Mail is running another round of early voluntary redundancies in his offer this spring, and if he is able to he will be applying. He has 27 years with Royal Mail and is the exact age that Royal Mail likes to try and 'ease' out 'lifers' of the business in favour of hiring younger, cheaper staff on poor employment contracts. Cue more wandering around in a daze.


I hope he gets it. The thought he could be retired and sitting on the patio by the summer makes me feel so happy for him. 


In the meantime, I'm number crunching and budgeting. All the money will be tucked away securely, and there will be very little spare money from our new income for any luxuries because I intend to go hell for leather pumping up my pensions and savings to get me ready to retire. I want to stop work sometime between 55-58 years old, at whatever point I can get the numbers to work out, so Martin and I can go and do some travelling while he is still young enough. 


Scary and exhilarating times ahead!

As part of the 31 NSD trial, I went through our expenses over the last few months and had a closer look at what we were spending money on.

A lot of money goes out every month on smallholding feed, equipment, fencing, medication and vet bills. I can mostly plan for the things needed but not emergencies requiring vets or fencing because the sheep have executed a mistimed Fosbury Flop and hurt themselves or got their heads stuck and thrashed until a fence post snaps. It is still worth keeping livestock as the quality of the meat and eggs is much better than what we could buy in shops.

The car is always springing something on us. February was two tyres for £103, neither planned, because we noticed the sidewalls had cracked. March was a new light unit for £15. We got away lightly last month.

The cat's vet costs are just ridiculous at the moment. Georgie was diagnosed with a thyroid problem at the beginning of March, had two sets of blood tests, expensive medication and a tooth extracted plus tooth cleaning. Fleagle has a problem with a lump under her tongue, which has necessitated three vets visits and two lots of meds. She goes back next week for an examination of that lump under anaesthetic and a tooth clean plus blood tests. The insurance should cover some but not all the costs of these two - Petplan would only offer us a shared responsibility policy for two elderly cats - so that's something but vet bills are now shaping up to be a regular expense so I need to find cheaper sources of medication for them instead of shelling out full price all the time.

I have discovered that we seem to pick up the tab for things more often that we should and overspend on people's birthdays and anniversaries. £30 for a relative's birthday lunch for the two of us turned into £90 last month because we picked up the tab for everyone. I can't even pretend alcohol was involved in the decision making on that one, we were drinking lemonade. I have realised we need to be a bit meaner because I can't remember the last time someone paid for us. If I budget £30 for a gift, we'll end up spending £40 by the time we take into account a card, maybe flowers and a birthday cake.

Finally, charity shops, car boot sales, etc. I've said before that these two end up not being such a cheap hobby, especially if you don't need the stuff you buy. You just end up piling more stuff into the house. I mostly gave up regular Sunday car boot sales before we moved here, as I was spending £20-£30 a week on bags full of stuff and cluttering up the house. Done the odd one as I've come across it but nothing planned. Unfortunately, regular charity shopping took its place. Analysis of the receipts shows I'm not just buying stuff in the charity shops, I might go into Savers or Boots and buy something, then I'll find something in the library in the For Sale section, then I'll have tea and cake at a local hospice cafe to support them and finish off my 'cheap day out' looking around Sainsbury's. Breaking that habit in Feb/March was the best thing I could have done, because that was shaping up to be a £20-£30 a week habit as well plus whatever I bought in Sainsbury's 'off-list'.

In all I can see where economies need to be made and habits need to be changed, because we're spending our early retirement. If we continue like this we will miss out on retiring early together, which we will always regret.

We need to refocus our commitment to our long-term plans.


There’s been a lot of kerfuffle in the press lately about FIRE (Financial Independence and Retire Early). It seems that some FIRE advocates have either been writing about or been sourced for comment about it and it's caused a big fuss. The newspapers, typically, have published articles based on the far extreme of FIRE and suggested that it is possible for us all to retire at 30/40 financially independent and never need money again if only we practice extreme frugality (or something like that). This is just click-bait ruse and to generate comments that keep the newspaper at the top of Google. The comments are as expected, depending on which newspaper you read, from the polite scepticism of Telegraph readers to the no-holds barred outrage and insults from Daily Mail readers.

The trouble is, the newspapers do no-one any favours but themselves by reporting in this way (perhaps reporting is too strong a word, story-telling may be more apt).

The consensus is the average Joe couldn’t possibly do this so why bother trying? To be honest, they’ve probably got the first bit right to a certain extent but it annoys me that it is seen as a binary choice. Either Financial Independence or bust! Suppose some of those people had a go, and the most they managed to accomplish was paying down all their debt and building up some savings so they feel more secure. Surely that’s better than throwing their hands up and not bothering?

A lot of the comments on the Daily Mail site were very telling. One man commented that “I might as well enjoy it as I could be dead tomorrow” because he earned £17,000 a year, his rent for a one-bed house cost him 40% of his salary so financial independence for someone in his position was ridiculous to aim for. No-one has said to him that if you earn £17,000 a year and spend 40% of your take home pay on your housing you should not be renting a one-bed house. This guy is renting so he has flexibility that homeowners don't have. Rent/mortgage should not be more than 30% of a take home salary. That’s what the banks work to when assessing mortgage affordability and it’s a good starting point for personal finances. If rental on a one-bedroom property is crucifying you, either downsize to a studio flat and save the difference or go up to a two-bed and share with a friend. Either way, the percentage of your take-home pay spent on housing comes down and you can breathe…and save.

I speak from experience. Years ago, before I met DH, I rented a two bedroom house on my own and my housing costs were 43% of my salary. Ouch! If this guy got his housing costs to 30% of his take home he could save 10%.

The attitude that “might as well enjoy the money, you could be dead tomorrow” is short-sighted and defeatist. Statistically you are NOT going to die tomorrow. I think averaged out across the entire population (taking into account age and health) it is something like 0.002% or 1 in 50,000 chance of dying tomorrow. If you spend everything you earn on consumer goods and services you will get to retirement age and have nothing but a state pension and a poorly performing private pension (if you didn’t opt out). If you’ve bought a house you might have that to fall back on and/or if you are very lucky you might have an inheritance from relatives. If you have neither and you opted out of a personal pension you’re going to endure a lot of financial pain at an age where it’s hard to ride that out. 

Anyway, it's no secret that DH and I want to retire early. I’ve explained my reasons why here.  I have a few FIRE advocates in my blogroll that I keep up with, HOWEVER, that does not mean I am going for Financial Independence. I realised some time ago that Financial Independence is not possible for us.

Financial Independence is defined as the point where the ‘income’ from savings and investments pay your monthly outgoings. You are considered to have reached Financial Independence when you have accumulated 30 x your annual expenses, which you can then take 4-6% a year of as your income. DH and I will not accumulate enough money to achieve those kind of numbers, which for us is around £600,000 without mortgage payments. Why?

  • We started late – I didn’t even think about retiring early until about 2009 at 36. 
  • We earn the UK average salary for a two-person household. We’re unlikely to ever earn megabucks because we’re not keen on the idea of the stress and responsibility that goes with it. We generate money on the side here and there when opportunities arise but generally we do not have the drive or energy to chase larger sums of money or climb ladders. That’s a conscious choice on our part.
  • We like the occasional meal out and want to have some interesting holidays over the next few years. I consciously cut some things to the bone to enjoy others.
  • We made the decision to take on another mortgage two years ago.  If we had stayed at the last place we would have been mortgage free in 2021. And miserable. I hated that house at the end. We moved to achieve a dream, albeit an expensive one.
  • We’ve benefited from rising property and financial markets over the last 10 years, which won’t last and we may be in for a bumpy ride during the next 10 years.
  • I only started a proper pension in 2010 and, due to probationary periods and redundancy, only have about 6-7 years contributions.


Taking into account all of that, what we can do is achieve financial comfort (and a nice chunk of FU money) earlier than 65, so that is our aim. We’re going to use whatever tips and tricks we can glean from every possible source, and combine that with solid budgeting, saving, tax and investing principles to secure a better financial future for ourselves. That better future is DH retiring at 62 and me at 55 and then carefully running down our money (we may work after this but the crucial point is it will be because we want to, not need to). 

This is different to true Financial Independence, in that we are not living off 4-6% of the total retirement pot every year. We’re living off a lot more than that every year so it will deplete over time. At some point we may have to do an equity release or downsize – we’re not living in penury when we own a house outright. We’ll use it if we have to and enjoy a comfortable retirement. 

I don’t believe the average Joe can achieve Financial Independence, but I do believe they can achieve financial comfort with no debt and a nest egg of FU money. That’s got to be worth going for.


This week I've had to decide whether to fix our mortgage for a further period of time to secure a low-ish interest rate or risk going onto a variable rate that is more than twice our current one, effectively doubling our mortgage interest payments. Not a tough choice really given our current savings and retirement goals, but how long to fix it for has required some mulling over.

The traditional length of time is 2 years and these deals usually have the lowest interest rate, with or without product fees. This time, however, I'm thinking of paying a little more and fixing for a longer 5-year deal. 

Why?

Lots of reasons. 

1. Interest rate rises are on the cards in the UK, probably starting around August time, so I want to lock in a decent rate now. If inflation suddenly started rising over the next couple of years and the Bank of England scrambled to successively raise interest rates to control it, we could be looking at paying hundreds of pounds more every month when our two-year fixed deal comes to an end. A 1% rise, while sounding small, is actually quite 'ouchy' for us. 

2. I don't know how secure my job is post-Brexit and the last thing I want is to have to prove my income for a new fixed mortgage deal in two years time when I may have just lost my job. I'm a great believer in 'Sod's Law', which states that whatever can go wrong will and with the worst outcome. 

3. Martin is at an age where he could be offered voluntary redundancy at any time. If he is and the deal is so favourable we take it, we don't want him to have to prove his income for a new fixed mortgage deal in two years. While we know we can meet our commitments, our lender's computer doesn't really 'get' frugal people and works on standard percentages of joint income. It will say 'no' when based on one income and savings due to the outstanding mortgage amount, even if we prove we are managing fine because we don't have the usual gym memberships, netflix subscriptions and loans. In five years time it could be a different story.

4. We may have a house price crash. Our area has quite slow growing house prices but should there be rampant inflation, recession, or a house price crash within the next couple of years, the value of our home could drop and our Loan-to-Value rate could mean we don't get the best deal. 

5. Five years gives enough time for any post-Brexit troubles to have ironed themselves out, for any mini-house price crashes and stock market tumbles to recover.

6. We'll be much more secure financially - another five years of pay rises, investments rising, savings' interest compounding, pensions maturing, and more capital paid down on the mortgage.  

So we're on a rate of 1.89% at the moment, looking at 2.29% for five years, and have submitted our financial paperwork to our broker to see if we will be accepted. 

It's not a given though. I'm no longer doing as much freelance work as I was 2-3 years ago, having opted to cut back on that to ensure I have time for gardening and smallholding tasks that give me pleasure. However, given that our overall savings and the value of the property having increased since we bought this place two years ago, I can't see there being a major problem. And having our savings account with our mortgage provider has the added bonus of letting them see how much we save regularly every month!

Martin and I are 10 percenters. That is, we are among the 10% of couples who have an age gap of more than 10 years. This never bothered us when we met 14 years ago, but the 12 year age gap is sure bothering me now I have to do retirement planning!

I've spent the last few months trying to get a handle on it. Along the way, I've managed to identify a number of important things to take into account as 10 percenters. I have not yet come up with a concrete strategy to work - to apart from spend less, save and invest more - so that is going to take some time over the next few months

The plan has to be based on my predicted lifespan

For couples of approximately the same age, retirement planning usually spans 30 years. Our has to span 40+. My life expectancy is 84, nearly 40 years away, and with advances in medical science I estimate that I will need to plan to live until I am at least 95. Seriously. The NHS calculate that UK women have a life expectancy of ~84 today but by 2030 - just 12 years away - that will rise to ~ 87. Yikes!

I have to retire early

Most couples make plans to retire together, perhaps do some travelling, but generally kick back and enjoy some time together. I will still be working when Martin retires and if I retire at the normal 65 he will have spent the greater part of his retirement alone and may not be in the best of health by then. Having a job working from home will help, as we can see each other every day, but going on holiday for long periods of time may not be possible while I'm still working. This means if we want to spend quality time together while DH is still fit and active, I have to retire early, 55 ideally, so we have to save and invest a lot more money to build a bigger pot.

We have to take bigger risks

To build up our retirement accounts, we have to take greater risks with the money to get better returns. This means holding (allocating) higher percentages of stocks and shares (equities) than would ordinarily be recommended. 

For a man of DH's age, it is usually recommended to hold no more than 40% in equities and 60% in bonds. For me it is the other way round, in fact, I could go higher with an 80/20 equities/bonds allocation as I am only in my 40s and therefore have a longer timespan to invest in. Some financial planners suggest it is important that investing is based on the age of the younger of the couple, not the older or their conservative approach will cause 'fiscal drag'.

We may have to delay taking the state pension

In the UK, for every nine weeks you delay taking the state pension you get a 1% increase, which equates to 5.8% increase if you delay for a full year. Depending on how we are building up our retirement accounts, this may have to form part of the planning. 

We have to consider long-term care costs

With Martin 12 years older than me, we may need to find the money for care costs, however, I may still need living expenses so we need to plan to ensure that we don't exhaust our accounts making sure he is cared for, leaving nothing for me. 

I will inherit less of Martin's pensions as I am a 'trophy wife'

Yes, that's right. Being 12 years younger means that DH's firm consider me a 'trophy wife' and, therefore, instead of getting 50% of Martin's final salary occupational pension when he dies, I get a reduced sum. That amounts to 2.5% less for every year between us over 10 years, so 5% less. 

We will have to use drawdown options, never annuity

All defined contribution pensions offer you a choice when you are ready to take them; you can either use the sum of the pension pot to buy an insurance policy that pays you a fixed amount for the rest of your life (annuity) or you can choose to drawdown a certain amount of money from the pot every year (3-5% a year perhaps) Drawdown pots can be inherited, annuities cannot. To maximise our income in retirement, it will have to be drawdown all the way so I we can inherit each other's full pension pots.

I'm going to need software to work it out

This is pretty complicated stuff, requiring Excel skills beyond my abilities, so I've recently bought a monthly subscription to a site called RetireEasy. You plug in all of your numbers for  household income, pensions, savings, etc., make estimates based on how much you think they will grow over time (very tricky!), and it obligingly spits out a snapshot that tells you whether what you think you have will be enough. See that big dip at 55 in the picture above? That's the age I set for me to retire. It's telling me we won't have enough to live on after we've paid the mortgage (our mortgage ends when I'm 62 and DH 64). I either have to retire later, we have to live on less or put more money in. I have a tendency to be pessimistic in my estimates so it will probably not be as bad as that but there is no harm preparing for the worst and hoping for the best.

One thing that RetireEasy doesn't have is a monthly breakdown of income, so on the side I am filling in the gaps. I may find as my knowledge grows and I want to test different possible outcomes in our retirement that RetireEasy is too basic, but for now it has been very helpful. 


It might seem a little early for a 45-year old to be blogging about retirement, however, this 45-year old has a husband who is 12 years older than her.  When there's a big age gap and one spouse is running up to the big 6-0, retirement planning is not easy to manage.

Up until 2015/16, we had a clear plan.


When I started blogging back in 2007 on my old typepad blog, it was a far off dream to own a smallholding where I could raise a few animals and my husband could rebuild his classic cars (the other love of his life!). In July 2016, we achieved that dream through frugality, money-saving and sheer hard work. For us, the sacrifices we made over the 11 years were worth the struggles. 

I decided to start a new website to celebrate this new chapter in our lives and chart our progress towards a new set of goals. We have turned our attention to retiring early so we can enjoy more time together than our full-time jobs and side hustles currently allow.

Like the old blog, this new one will encompass a wide range of topics, including frugality, money-saving, budgeting, investing, personal development, crafting, make do and mend, smallholding skills, growing fruit and veg, raising animals, and retirement planning.

At the same time we intend to live a little more - the last few years at the old house we were so consumed with money-saving we rarely took time out for ourselves. Now we have my 84-year old mother-in-law living with us, taking regular breaks will be paramount to maintaining our health and wellbeing. 

Always on a budget though!
Powered by Blogger.

Read my old blog